
Share with your CTO
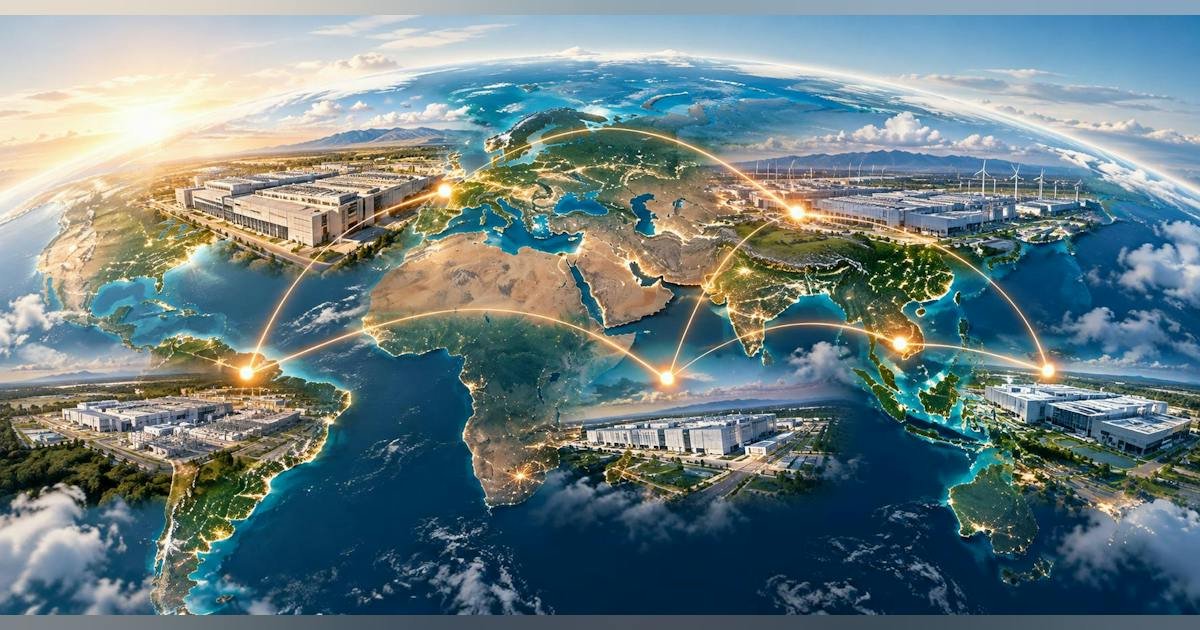
The global AI infrastructure buildout is fracturing into five distinct execution models, and the gap between announced capacity and delivered compute is becoming the number that matters most. Asia-Pacific alone carries roughly 26.5 GW in its development pipeline as of H1 2026, with only 4.8 GW actually under construction. Spain is reforming permitting, India is racing to match capital commitments with electrical readiness, and Singapore is rationing capacity selectively. Every market is solving the same problem differently, and none of them has cracked it yet.
What this means for your business
If your infrastructure roadmap assumes that announced capacity in a given region equals available capacity, you’re planning against a fiction. The 21.7 GW sitting in Asia-Pacific planning stages represents commitments that still require power interconnection, transmission upgrades, equipment delivery, and regulatory clearance before a single GPU goes live. Companies with aggressive international expansion timelines, whether for training clusters or inference platforms closer to end users, should be stress-testing the delivery schedule behind the headline number, not the headline number itself.
The supply chain angle is the one most North American CTOs are underweighting. Transformers, high-voltage switchgear, and advanced cooling systems don’t have a separate global inventory for international projects. A hyperscale campus breaking ground in Malaysia competes for the same 18-month transformer backlog as a campus in Northern Virginia. That’s already a constrained supply chain, and every gigawatt committed abroad tightens it further. The CTO whose procurement team isn’t tracking international buildout velocity alongside domestic lead times is operating with an incomplete picture of their own delivery risk.
The divergent national strategies, Brazil demanding direct economic benefit through incentives, Singapore allocating capacity through a selective approval process, China co-locating compute next to generation assets, are worth reading as a preview of the policy environment coming to North America. Host governments are learning that AI infrastructure is leverage, and the era of permissive, subsidy-light data center development is already ending in several markets. If your five-year compute strategy includes greenfield development in any jurisdiction where you don’t already have an operating relationship with regulators, the international precedents set right now are the baseline you’ll be negotiating against.
Concept deep-dive: Execution gap
The execution gap is the distance between megawatts announced in a press release and megawatts energized and serving workloads. It exists because permitting, utility interconnection, equipment delivery, and construction each carry independent timelines that compound rather than compress. Think of it as the difference between a building permit and a certificate of occupancy, multiplied across power, fiber, and cooling infrastructure simultaneously. For capacity planning, the execution gap means announced supply is a ceiling, not a floor.
Based on reporting from DCF Global: Five Markets Redrawing the AI Infrastructure Map, originally published 2026-10-09 15:54:00.