
Share with your CEO
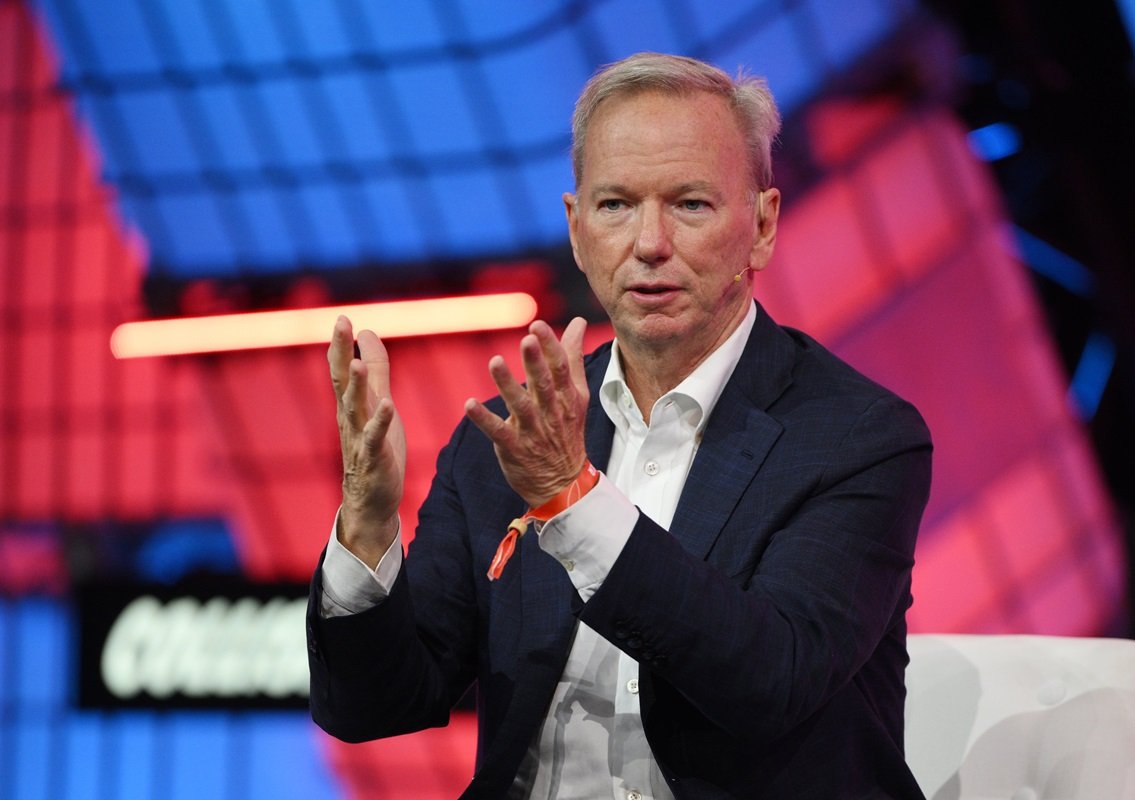
Eric Schmidt’s reported 1% stake in Anthropic, acquired at the company’s $461 million Series A valuation in 2021, could be worth $20 billion if Anthropic reaches a $2 trillion public market valuation at IPO. That’s a speculative ceiling, not a floor, but the gap between Schmidt’s entry price and any plausible IPO range already makes his position one of the most valuable early bets in AI venture history. The comparison that matters: Dario Amodei, who built Anthropic, holds roughly 2%.
What this means for your business
The Amodei-Schmidt ownership comparison is the most telling number in this story. A co-founder and CEO holding only twice the equity of a single Series A check writer tells you how much dilution Anthropic absorbed raising the capital that got it here, and that dynamic is now baked into the valuation math every enterprise buyer and board member faces. If you’re currently negotiating multi-year Claude contracts or enterprise agreements, you’re pricing in a company that has already given away enormous equity to reach this scale.
The $2 trillion figure is doing a lot of rhetorical work. For context, that’s roughly where Apple sat when it was the world’s most profitable hardware and services business, not a company still burning cash to train frontier models. Anthropic’s actual revenue trajectory, its ability to convert enterprise pilots into durable contracts, and its gross margins on API and Claude.ai business are what will set the IPO range. The gap between private-market narratives and public-market scrutiny tends to compress fast once an S-1 lands and analysts can model actual unit economics. Schmidt wins big at almost any reasonable exit; the open question is whether enterprise buyers will be left holding contracts priced into a valuation that public markets discount by 40%.
The IPO will function as a pricing benchmark for the entire AI platform layer, whether Anthropic wants that role or not. If public markets assign Anthropic a valuation that implies meaningful skepticism about AI revenue durability, every renewal conversation at OpenAI, Google, and Cohere gets harder for the vendor and easier for the buyer. That’s the outcome worth watching, not Schmidt’s paper gains. I’d revise this view if Anthropic files an S-1 showing gross margins above 60% and net revenue retention above 120%, two numbers that would justify the premium and shift negotiating leverage back to the vendor.
Based on reporting from Eric Schmidt Could Gain $20bn From Anthropic IPO if AI Startup’s Valuation Hits $2tn, originally published 2026-10-21 00:03:00.