
Share with your CIO
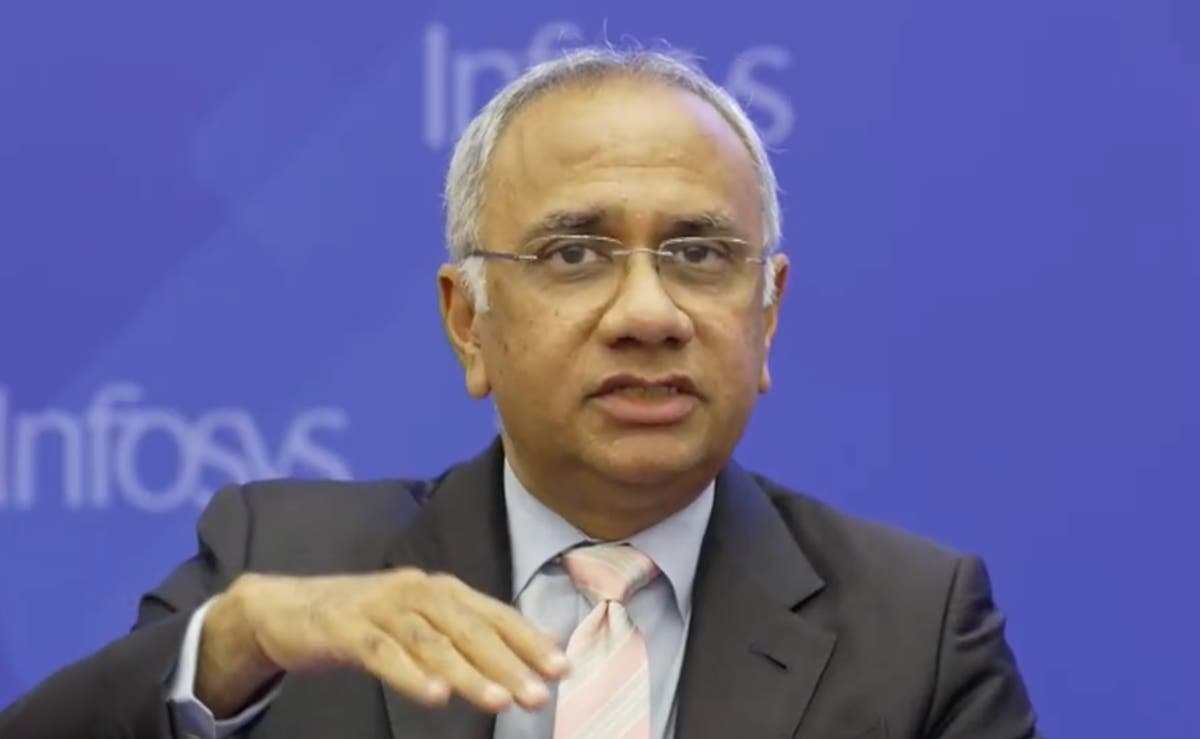
Infosys is betting that AI services revenue, now 10.5 percent of total revenue and growing 29 percent sequentially, is the clearest proof point that enterprise AI has crossed from pilot to production. CEO Salil Parekh disclosed two mega deals in Q2 FY27, including a $2 billion-plus net-new seven-year contract with a large international company expected to add more than one percentage point to revenue growth next year. Total large-deal TCV reached $5.2 billion, 62 percent net-new, while overall revenue came in at $5.145 billion with operating margin holding at 21 percent.
What this means for your business
The story here isn’t Infosys’s quarter, it’s what their pipeline composition reveals about where enterprise AI spending is concentrating. When a firm books $5.2 billion in large deals, with nearly two-thirds coming from clients who haven’t previously spent with them, that’s a signal that incumbents are losing the AI conversation. If your organization is still running AI workloads through a legacy IT services relationship on autopilot, the renewal logic you applied three years ago may no longer reflect the competitive options your peers are actually exploring.
Infosys is positioning its Topaz Fabric, an orchestration layer that routes AI workloads across different models to minimize cost per token while maximizing output quality, as the reason CIOs should standardize on Infosys rather than assemble a multi-vendor stack themselves. That’s a defensible pitch during a period when model fragmentation is genuinely painful, and switching costs are high enough that whoever wins the architecture decision early tends to hold it. The risk is that Topaz is a proprietary wrapper around models Infosys doesn’t control, which means the differentiation narrows every time OpenAI, Anthropic, or Meta improves their own tooling.
The client mix disclosed this quarter, Mondelez on supply chain, Telia on network operations, KnitWell on customer engagement, spans enough verticals to suggest Infosys isn’t winning in one sector on one use case. That breadth matters because the recurring failure mode in IT services is a firm that looks strong in a single domain and then struggles to cross into adjacent ones. The falsification condition here is simple: if AI revenue growth decelerates sharply next quarter without a corresponding margin expansion, it signals that Infosys is buying these deals rather than earning them, and the ecosystem-integrator story starts to look like a rebadging exercise.
Based on reporting from Infosys Q2 Earnings: ‘We remain the preferred AI strategy and deployment partner for our top clients,’ CEO says, originally published 2026-10-23 07:56:00.